
Summary
- A big week, but not a fundamental break. CLARITY was delayed, but U.S. crypto regulation kept moving through the SEC, CFTC and Congress. The Fed may hike another one or two times, but there is still little evidence of a new large tightening cycle.
- Institutional demand turned cautious, not bearish . ETF outflows appeared around the week’s major events and Strategy paused buying for a second week, but ETF net inflows returned quickly on Sep. 17, showing demand remained resilient.
- The market entered the volatility with much less leverage. Futures OI had already fallen sharply, liquidations flushed more longs after the CLARITY vote, while funding remained positive but moderate. With leverage significantly reduced, the market structure looks healthier despite the volatility.
A Big Week, But Not a Fundamental Break
It was one of the most event-heavy weeks of the year.
- Sep. 15: The CLARITY Act failed to advance in the Senate.
- Sep. 16: The Fed raised rates by 25bp to 3.75–4.00%, its first hike since 2023.
- Sep. 16: A House committee advanced legislation related to the Strategic Bitcoin Reserve.
- Sep. 17: The SEC introduced its Innovation Exemption, opening the door for tokenized U.S. stocks to trade through permissioned onchain AMMs and liquidity pools.
- Sep. 17: The CFTC eased requirements for qualifying passive software providers.
Some were negative. Others were clearly positive. After all of them landed within just a few days, what has actually changed for the market, and what matters next?
CLARITY Stalled. Crypto Regulation Did Not.
The CLARITY Act failed to advance on Sep. 15, meaning its path into law may now have to wait until 2027.
But the SEC and CFTC introduced new measures that expanded the regulatory room for crypto and tokenized assets. At the same time, Strategic Bitcoin Reserve legislation continued moving forward in Congress.
One failed vote did not stop the broader U.S. crypto regulatory process. CLARITY has been delayed, not died. If it returns in 2027 under a stronger crypto market, its eventual passage could become another meaningful regulatory catalyst.
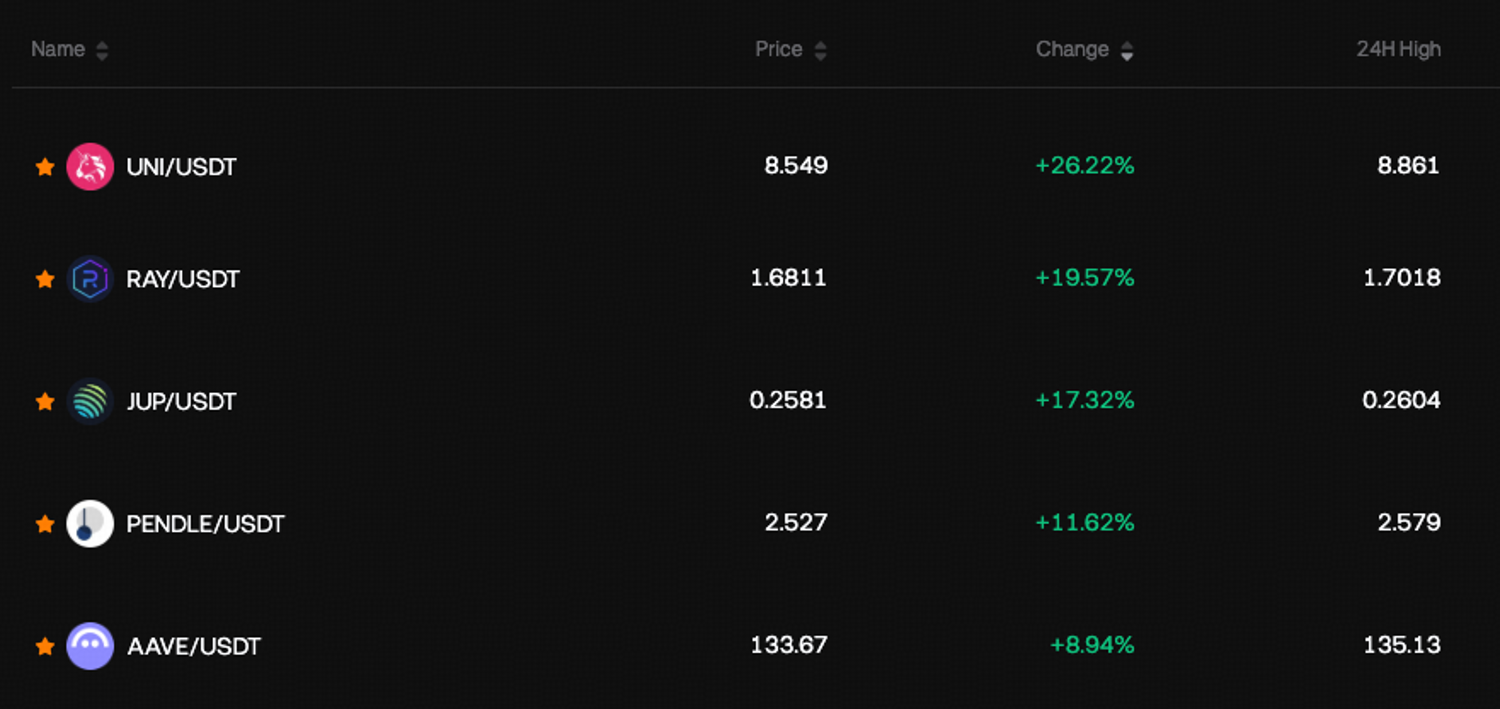
But the market does not need to wait until 2027. The SEC and CFTC moves have already reactivated the long-dormant DeFi trade. DeFi tokens rallied broadly after the announcements, with UNI up around 27%.
One Hike Does Not Make a New Tightening Cycle
The bigger macro risk now is whether one Fed hike turns into several more.
Another one or two hikes are still possible. Growth remains solid, employment is stable, and inflation remains above target.
But today’s inflation environment is different from the previous tightening cycle. Current pressure is more concentrated in sticky services inflation and supply-side factors such as energy, tariffs and geopolitics.
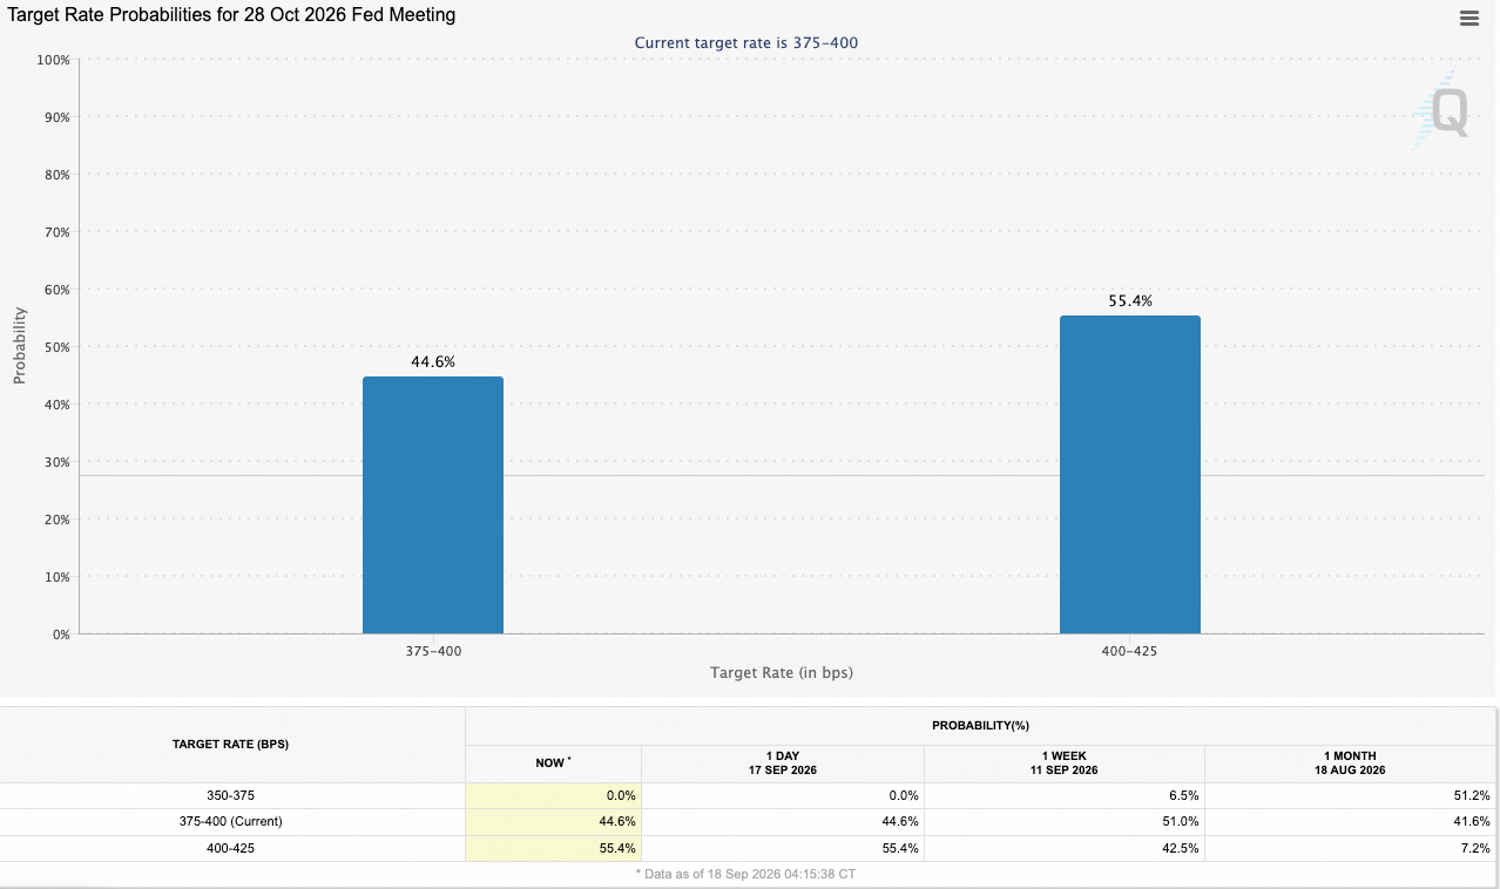
The market is now roughly split on whether the Fed will hike again in October, with the probability around 50%.
Another 25–50bp of tightening is therefore possible. But that does not automatically mean the economy is entering another large tightening cycle like the early 2020s.
What Matters Next
After one of the year’s busiest macro weeks, neither of the two biggest concerns has turned into a fundamental break.
U.S. crypto regulation is still moving forward despite the CLARITY delay. And while the Fed has raised rates by 25bp, the evidence for a prolonged hiking cycle remains much weaker.
From here, three things matter most:
- Geopolitics and energy: Whether geopolitical tensions ease enough to bring oil prices and inflation pressure lower.
- The U.S. midterms: How the approaching election changes the political environment for fiscal policy, regulation and markets.
- Crypto regulation: Whether the SEC, CFTC and Congress continue advancing the broader U.S. crypto framework while CLARITY remains delayed.
The market has absorbed a huge amount of event risk in one week. Yet asset prices remain remarkably resilient.
Bitcoin and ETH have both held up despite the regulatory and macro shocks, while the broader crypto market continued to rally. A volatile week, but resilient prices and new opportunities are still emerging.
- $ZEC (+32%) : Privacy narrative and renewed capital inflows.
- $UNI (+46%) : SEC support for AMMs, tokenized assets and the Robinhood narrative.
- $ARB (+46%) : Robinhood Chain and the tokenization narrative.
- $NEAR (+40%) : Renewed momentum following its strategic repositioning.

Flows Turn Cautious, Demand Holds
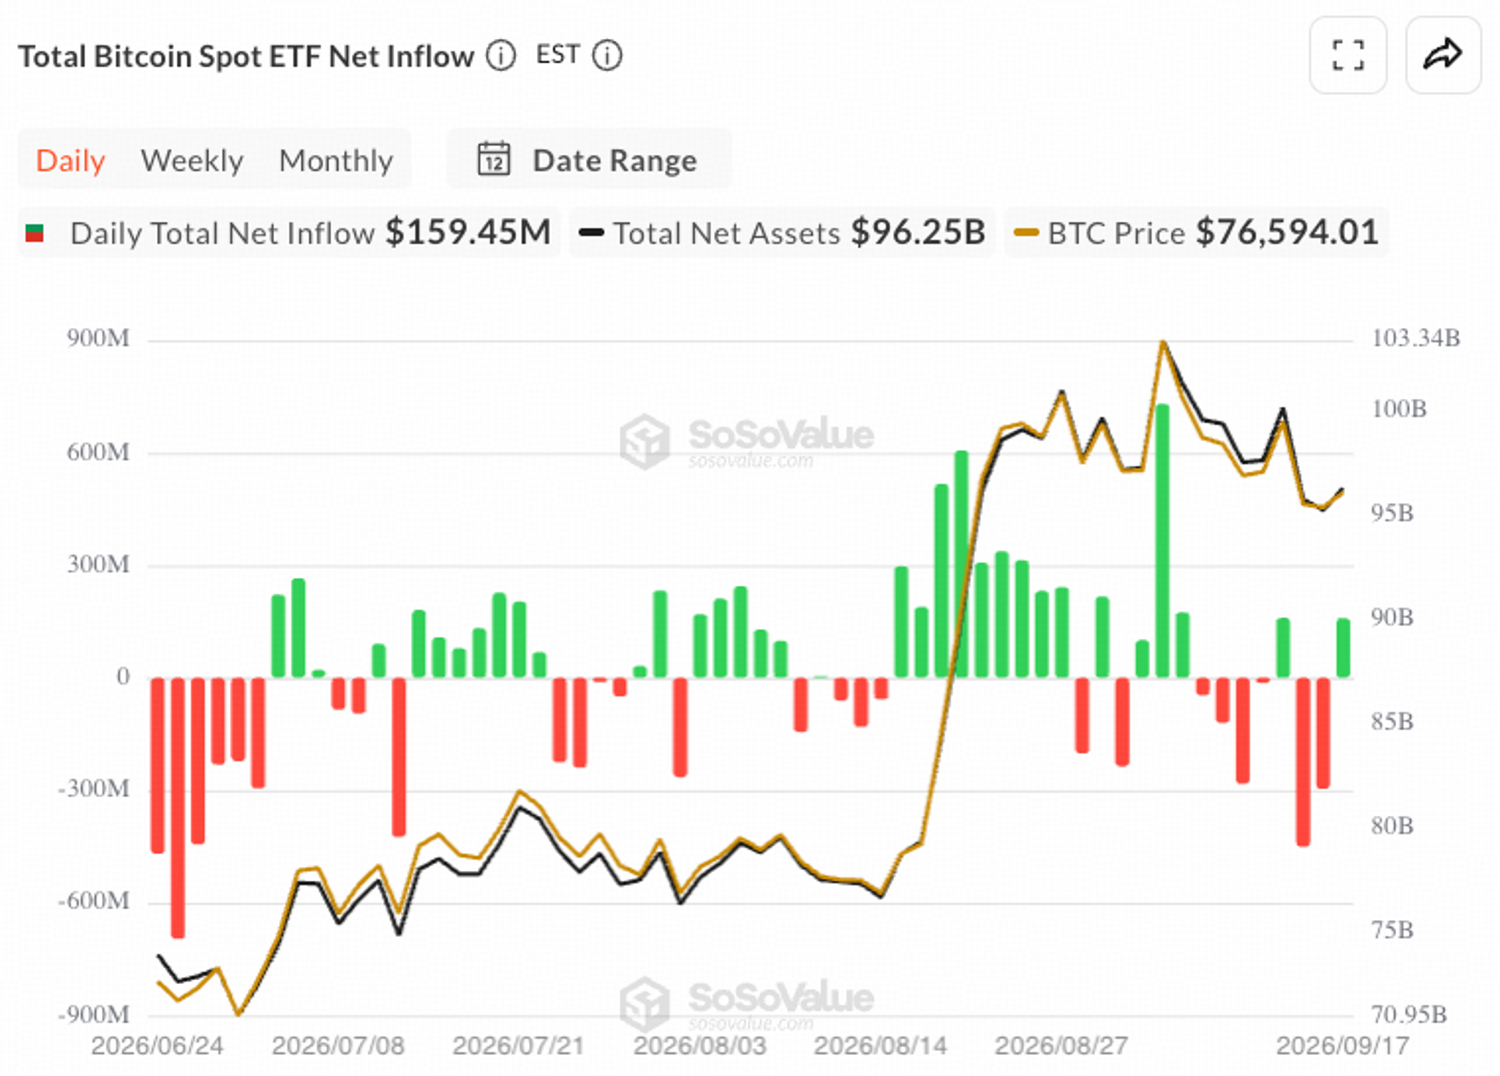
Bitcoin ETF flows weakened this week, with net outflows on Sep. 15–16 amid the failed CLARITY Act vote and the Fed rate hike. Some caution had already emerged ahead of these events, suggesting part of the risk was priced in beforehand. More importantly, net inflows resumed on Sep. 17, showing that institutional demand remained resilient despite the volatility.
Strategy made no Bitcoin purchase for the week to Sep 13, its second straight week on pause, likely a response to the elevated volatility around the two events.
With major macro and regulatory events driving volatility this week, institutional flows were generally more cautious. Still, the quick recovery in ETF inflows suggests underlying demand has not materially weakened.
A Priced-In Hike Meets a Deleveraged Market
- Open interest
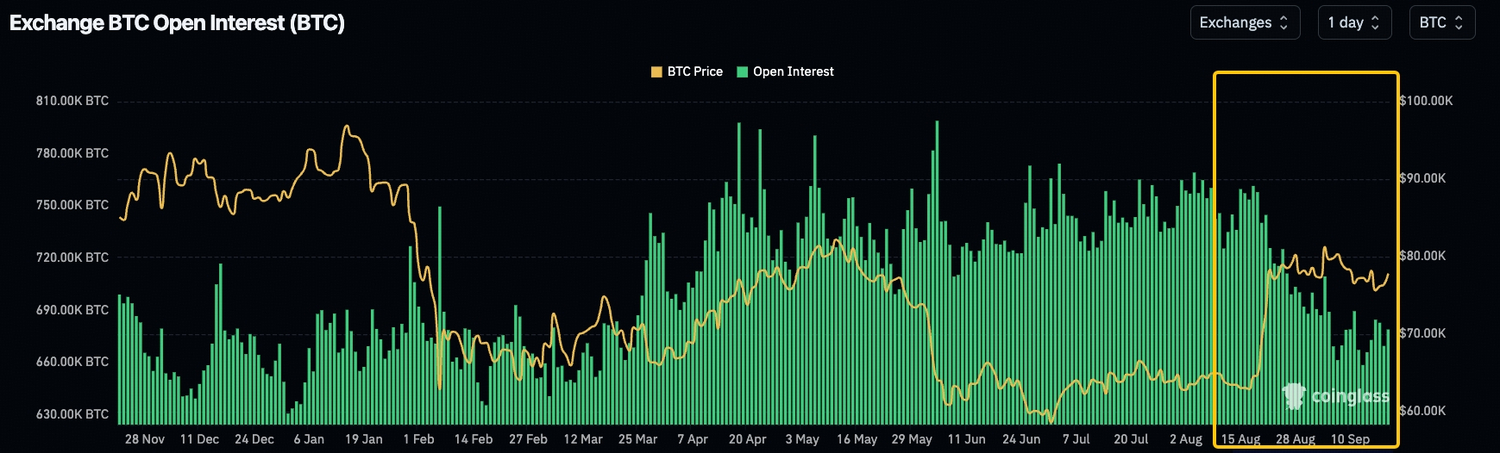
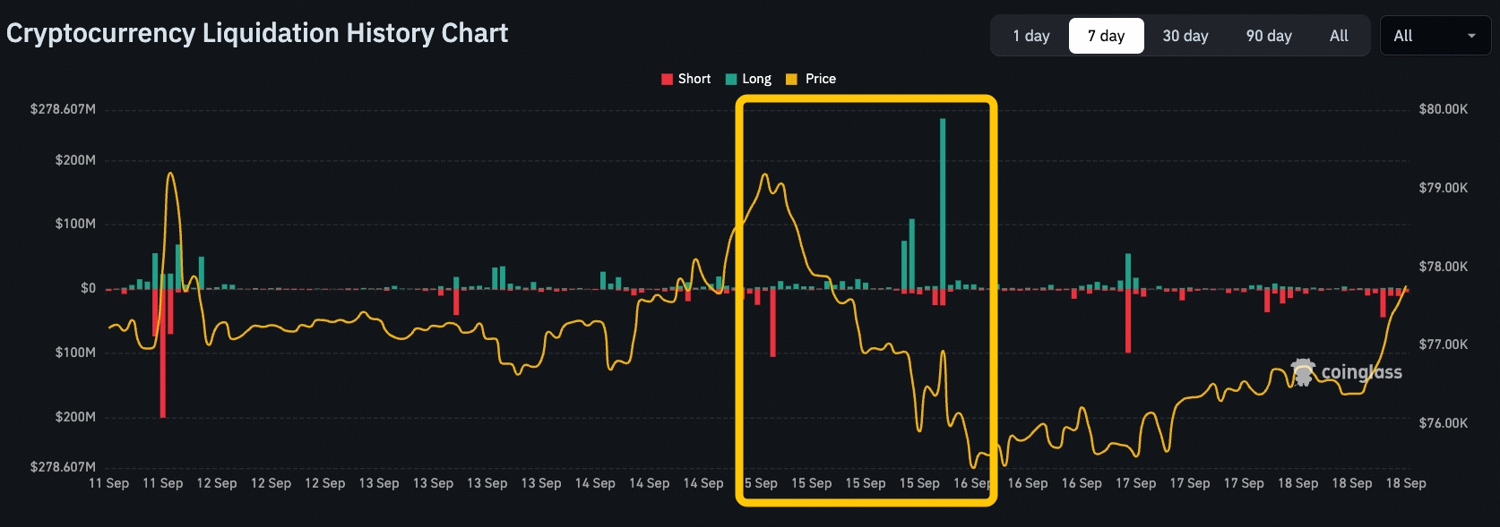
Aggregate crypto futures OI fell about 13.5% between Sep 3 and Sep 11, with roughly 43,000 BTC of leveraged positions unwound, and coin-denominated BTC OI now sits about 100K BTC below its mid-August high. It is the sharpest deleveraging since 2023. The rally was driven by spot, and what leverage remained got flushed on the way down.
- Liquidations
The one violent day was Sep 15. The failed CLARITY Act cloture vote triggered well over half a billion dollars of long liquidations in 24 hours, split roughly evenly between BTC and ETH.
- Funding
Perpetual funding stayed positive through the week, averaging roughly 0.006% to 0.008% per 8 hours, well below the 0.01% line that usually marks broad bullish positioning. Longs are paying, but not much.
Week Ahead
- Sep 21: PBoC Rate Decision
- Sep 23: US September Flash PMIs
- Sep 24: SNB Rate Decision
A quiet week after the hike. Wednesday's flash PMIs are the only fresh read on US activity before August PCE lands on Sep 30, with October hike and hold odds near 55/45 after Warsh's press conference. A soft print would trim those odds and give Treasury yields room to ease. Fewer hikes priced in means a better backdrop for risk assets, including Bitcoin and AI stocks.
Disclaimer: The information provided herein does not constitute investment advice, financial advice, trading advice, or any other sort of advice, and should not be treated as such. All content set out above is for informational purposes only.