
[NEW] Whale Monthly Edge Report — September 2026
This report covers the data window through September 20, 2026. The rally broadened beyond Bitcoin, supported by stronger spot inflows, lower leverage and rising altcoin participation. Two signals define the period: BloFin funding remained positive across all 10 tracked contracts, with higher carry concentrated in altcoins, while VIP positioning became increasingly defensive.
Part 1: Executive Summary
Key Market Takeaways
- September’s rally broadened beyond Bitcoin. Stronger spot inflows, lower leverage and rising altcoin participation supported a healthier risk-on environment.
- Further Fed tightening is the key macro risk. The Fed delivered its first rate hike since 2023, with resilient growth and elevated inflation keeping further increases in play. Markets priced roughly a 70% chance of another October hike, creating a potential test for the rally.
- Regulatory progress continued despite CLARITY’s setback. The bill stalled in the Senate, pushing the legislative timeline back. Meanwhile, SEC and CFTC initiatives continued advancing the framework for tokenized assets and crypto market infrastructure.
BloFin Whale Read
- One-Month Funding (Aug 17 - Sep 20): Broadly positive, with stronger demand for altcoin exposure. All 10 tracked contracts recorded positive average funding. PEPE carried the highest rate and BTC the lowest, consistent with risk appetite expanding beyond Bitcoin.
- 8-Week Net Delta (Jul 27 – Sep 20): VIPs became more defensive as the rally broadened. SOL shifted decisively net short, ETH and HYPE weakened, and ZEC’s long bias moderated substantially. BTC remained comparatively resilient, staying net long throughout the final four weeks.
- BloFin vs Binance (Sep 14–20): Cautious VIPs alongside expensive long exposure. BloFin VIPs were less bullish across BTC, ETH and SOL, while venue-wide funding exceeded Binance’s on all three. Hedging and funding collection could partly explain this pattern, although the data cannot establish traders’ motives.
What to Watch Next Month
- Bitcoin is showing striking resilience as global yields surge. Gold and silver have suffered sharp losses this month, while BTC remains relatively stable. Higher yields increase the opportunity cost of holding non-yielding assets. Bitcoin’s limited reaction suggests demand is absorbing that pressure, although a lasting shift in its sensitivity to rates remains unproven.
- The October Fed meeting is the next test, with markets leaning toward another hike. A second consecutive increase, particularly alongside hawkish guidance, would test whether BTC can sustain its resilience as monetary conditions tighten.
Part 2: Market Context
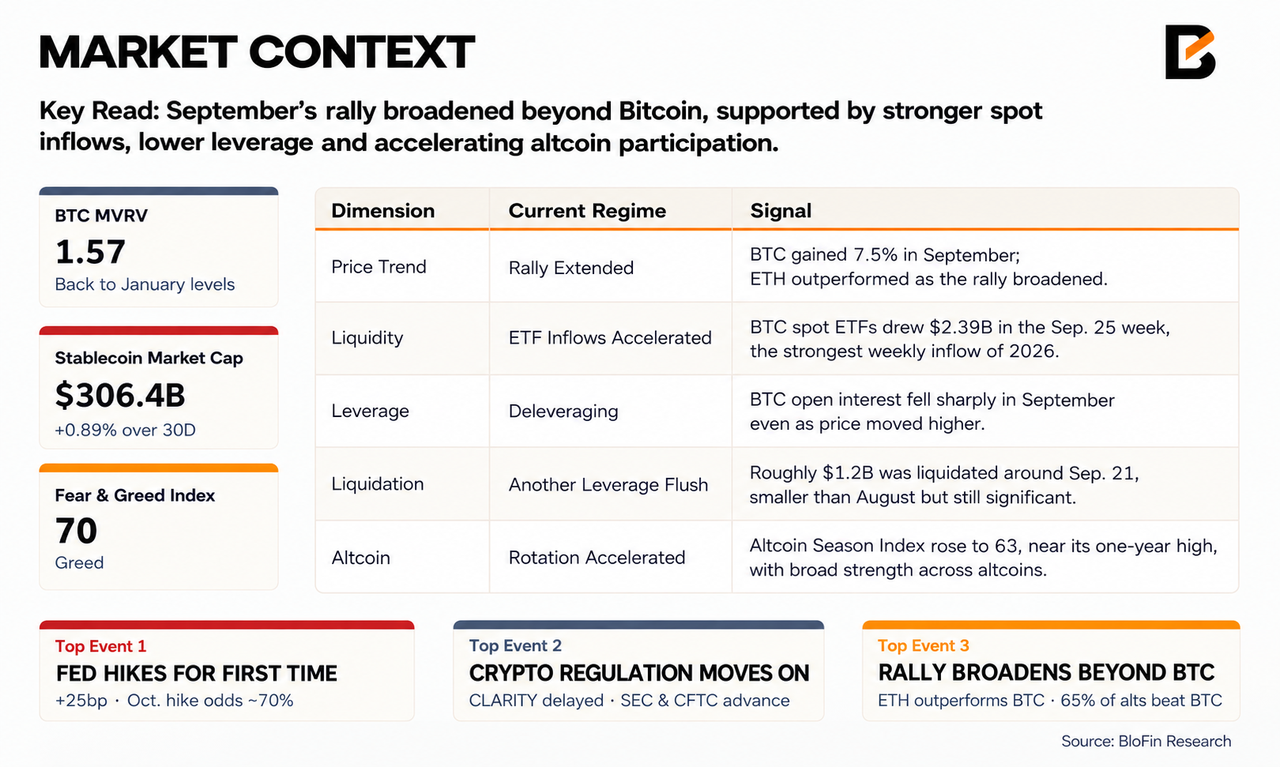
September broadened the rally beyond Bitcoin: stronger spot inflows, lower leverage and rising altcoin participation pointed to a healthier, more broadly supported risk-on environment.
Top Market Events of the Month
- The Fed delivered its first rate hike since 2023.
The Fed raised rates from 25bp to 3.75%–4.00%, its first hike in more than three years. Growth remains solid and inflation elevated, keeping further tightening on the table. After strong September PMI data, October hike odds climbed to around 70%, making the next move the key macro risk for crypto.
- CLARITY stalled, but crypto regulation kept moving.
The CLARITY Act failed to advance in the Senate, with another legislative attempt now unlikely before 2027. But the SEC and CFTC quickly moved ahead under existing authority, including new measures for tokenized assets and crypto market infrastructure.
- The rally broadened well beyond Bitcoin.
Total crypto market cap briefly reclaimed $3T for the first time since January. BTC gained about 8.8% in September, while ETH performed even better, rising around 9.1%. Beyond the majors, 65% of altcoins outperformed BTC over the past month, showing that the rally had broadened across the market.

Read the full report
Log in to access your Free Pass and VIP reports.