
Summary
- The rally is broadening beyond Bitcoin. Total crypto market cap briefly reclaimed $3 trillion, 90% of altcoins outperformed BTC over the past week, and MVRV crossed back above its one-year average in a pattern similar to the major cycle shift seen in 2023. UNI, NEAR and AVAX have all gained roughly 60% to 100% in 2 weeks.
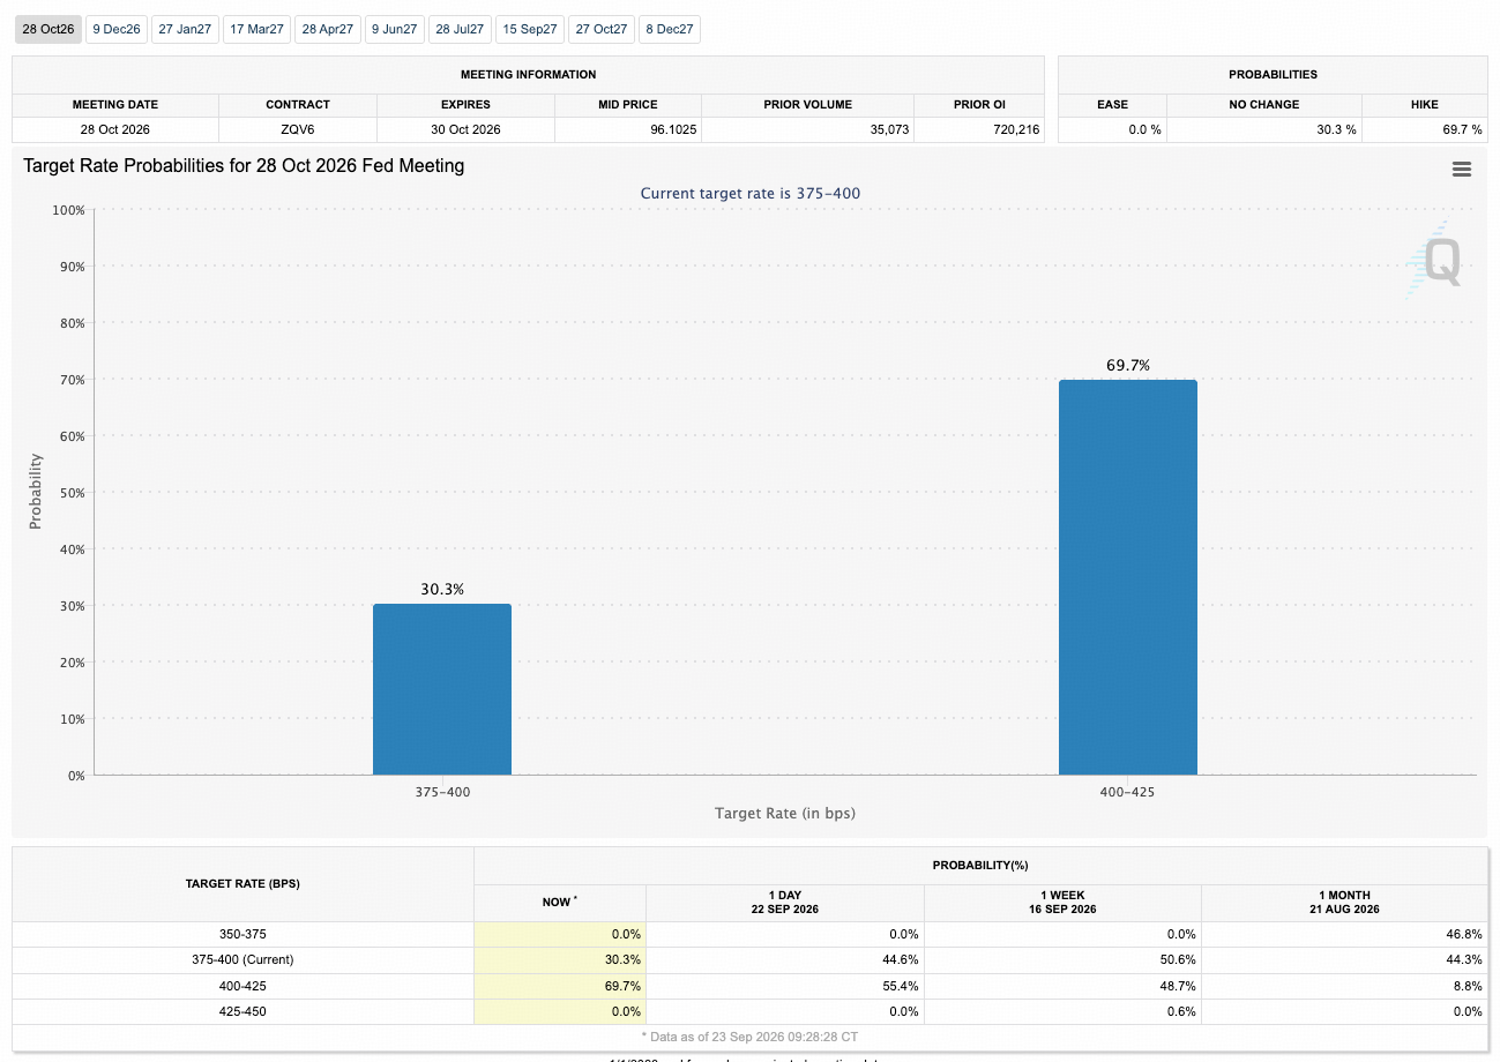
- Macro remains the main risk. A five-year high in September flash PMI pushed October Fed hike odds from roughly 49% to nearly 70% and the 10-year yield above 5.1%. BTC subsequently pulled back 4.0%, from above $87K to around $84K, alongside gold and U.S. equities.
- So far, the pullback has not broken the bullish setup. BTC leverage has fallen from the rally high, funding remains broadly positive, and ETF inflows continue through correction. The macro shock has pushed prices lower, but has yet to trigger a broader deterioration in crypto positioning.
Bitcoin’s Price Action This Week
Bitcoin’s price action this week was shaped by improving crypto sentiment, strong institutional flows and, ultimately, renewed rate pressure.
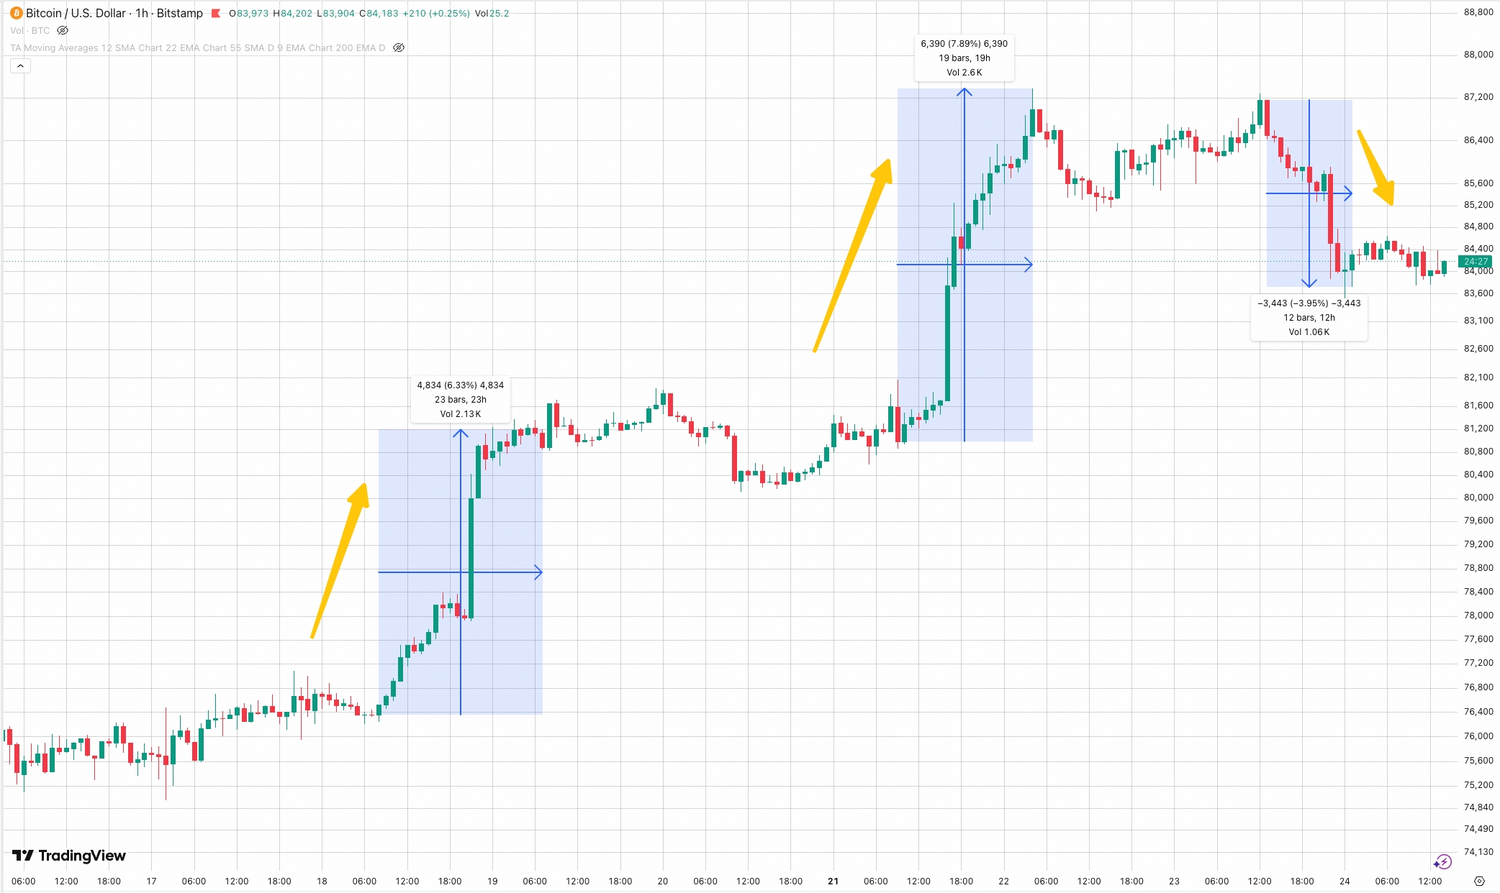
- Sep 18 to 19: BTC broke out of its post-FOMC range and climbed 6.3%, from around $76K to $81K. The rebound followed the SEC’s new Innovation Exemption, alongside renewed inflows into spot Bitcoin ETFs.
- Sep 21 to 22: The rally accelerated, with BTC surging another 7.9%, from around $81K to above $87K, its highest level since January. The move triggered a major short squeeze, with $648M in crypto short positions liquidated, while U.S. spot Bitcoin ETFs recorded $999M in net inflows on Sep 21.
- Sep 23 to 24: Macro pressure returned. September flash PMI showed the fastest U.S. business growth in more than five years, pushing October Fed hike odds above 70% and the 10-year Treasury yield above 5.1%, its highest since 2007. Risk assets sold off, and BTC pulled back 4.0%, from above $87K to around $84K.
The Bull Case: Signs of a Bigger Cycle
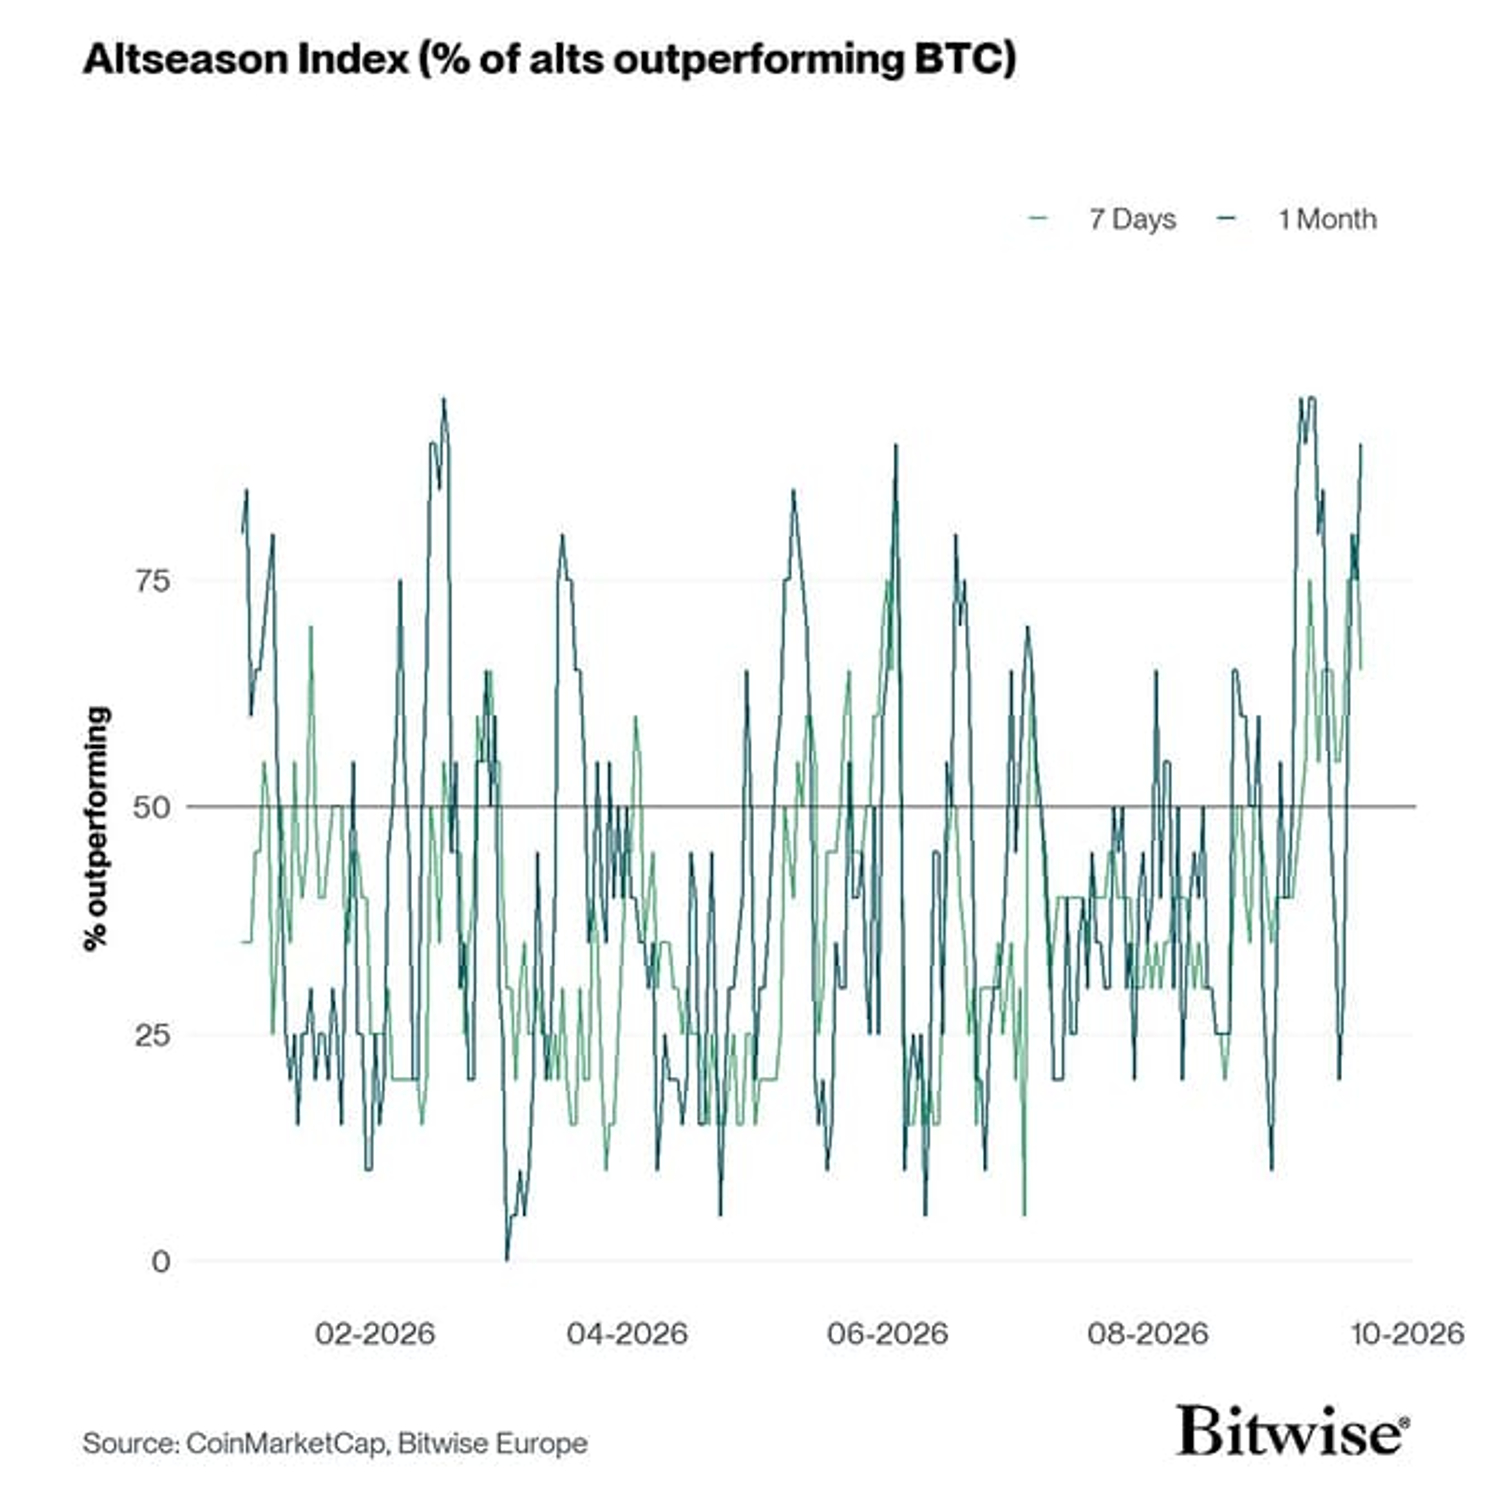
The rally is broadening beyond Bitcoin. Total crypto market capitalization briefly reclaimed $3 trillion this week for the first time since January. More importantly, 90% of altcoins outperformed Bitcoin over the past seven days, while 65% are still outperforming BTC on a one-month basis. The breadth of the move suggests this is no longer just a Bitcoin-led rally.
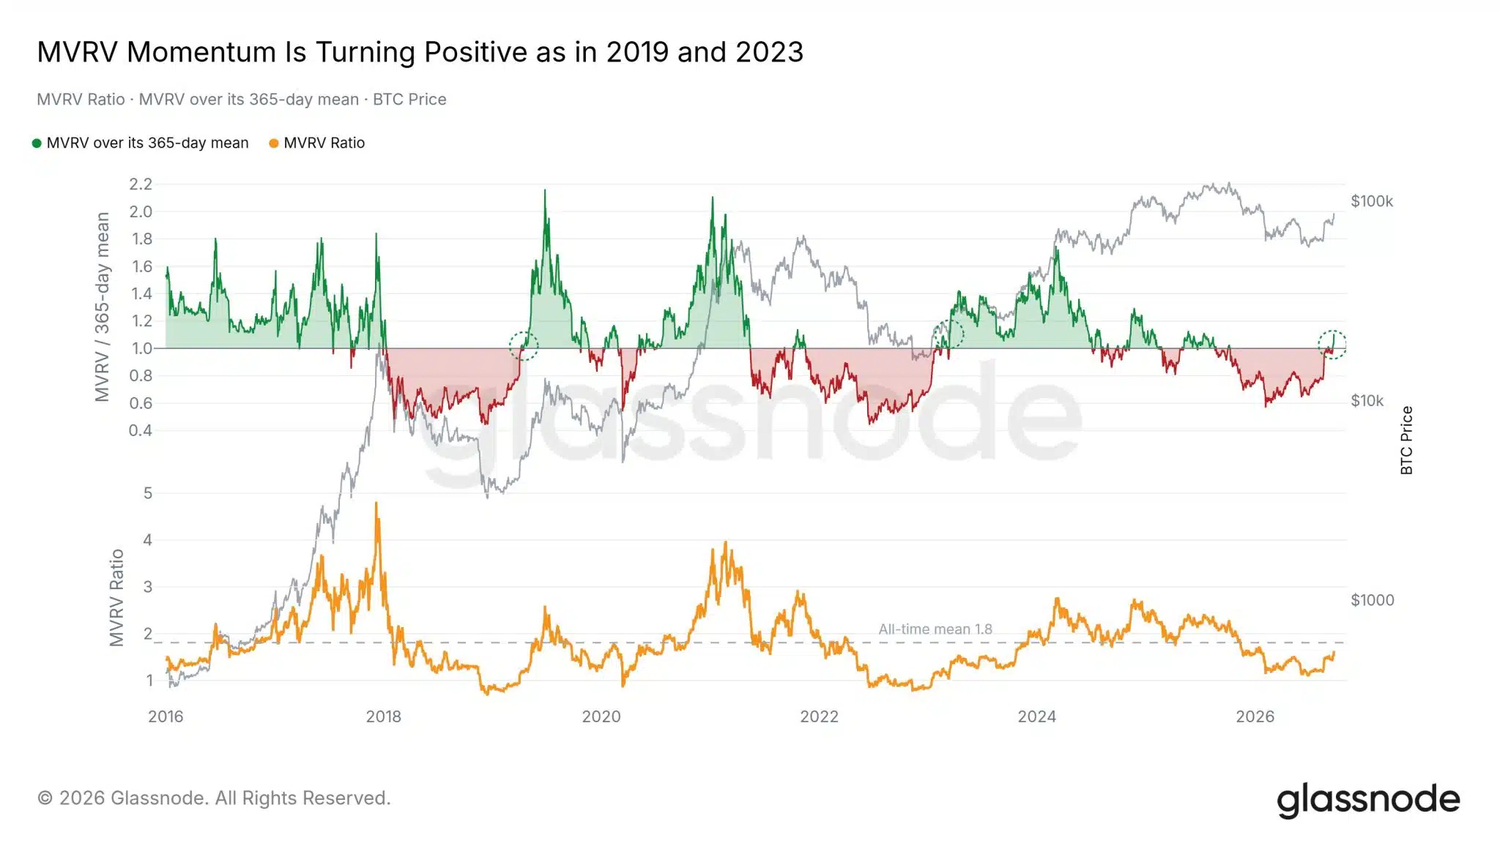
MVRV is flashing another positive signal. Bitcoin’s MVRV has crossed back above its 365-day average after an extended period below it. Similar crossovers appeared in 2019 and 2023, around major transitions from market contraction into expansion. At around 1.5, MVRV remains below its long-run mean of 1.8 and far below the readings above 4 seen around previous cycle peaks. Momentum is improving without valuations yet looking historically stretched.
The strength is also showing up clearly in individual altcoins.
- UNI has gained more than 80% since early September, reaching $10.8 this week. Its strongest move followed the SEC’s Innovation Exemption, as markets repriced Uniswap’s potential role in tokenized-stock trading through permissioned AMMs.
- NEAR has nearly doubled in about two weeks, rising from around $2.4 to a high of $4.7. The rally has coincided with renewed attention on NEAR Intents, confidential trading and its broader cross-chain execution strategy.
- AVAX has climbed roughly 60% in two weeks, reaching $11.7, as institutional tokenization returned to focus, including ICE’s testing of Avalanche technology for a potential tokenized-securities platform.
The Pressure: Macro Turns Hawkish Again
The biggest risk to the rally remains macro.
September’s U.S. flash Composite PMI jumped from 56.0 to 58.4, its highest in more than five years, while input cost growth accelerated to a near four-year high. Stronger growth combined with renewed price pressures reinforced expectations that the Fed could continue tightening.
Markets reacted quickly. The probability of another Fed hike in October climbed from roughly 49% a week ago to nearly 70%.
The pressure quickly spread across major asset classes:
- Treasuries: The 10-year yield surged above 5.1%, its highest level since 2007.
- Bitcoin: BTC dropped 4.0%, from above $87K to around $84K.
- Gold: Spot gold fell below $4,300, losing about 1.6% on the day.
- Equities: The S&P 500 fell 0.8%, while the Nasdaq 100 lost 0.9%.
- U.S. Dollar: The dollar index strengthened above 101.
The message is straightforward: crypto momentum has strengthened, but the Fed remains the biggest macro constraint on how far the rally can run.
Why the Pullback Hasn’t Broken the Bullish Setup
Despite the macro-driven pullback, positioning underneath the market has remained relatively constructive.
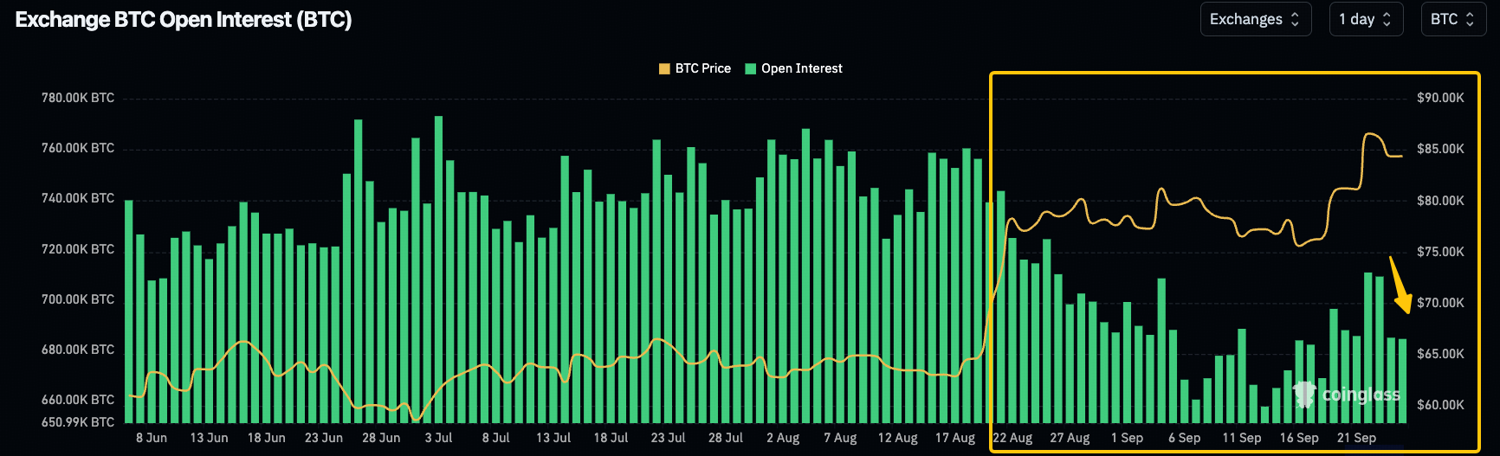
Leverage remains contained. BTC open interest rose to around 710K BTC as Bitcoin approached $87K, but quickly fell back to roughly 685K BTC after the pullback. That remains well below the 780 to 800K BTC levels seen earlier this year, suggesting leverage has not rebuilt to previous extremes.
Funding remains broadly positive. Across major exchanges, seven-day accumulated funding rates remain positive for most major crypto assets. Traders are still positioned toward the long side, while the recent correction has not triggered a broad shift into negative funding.
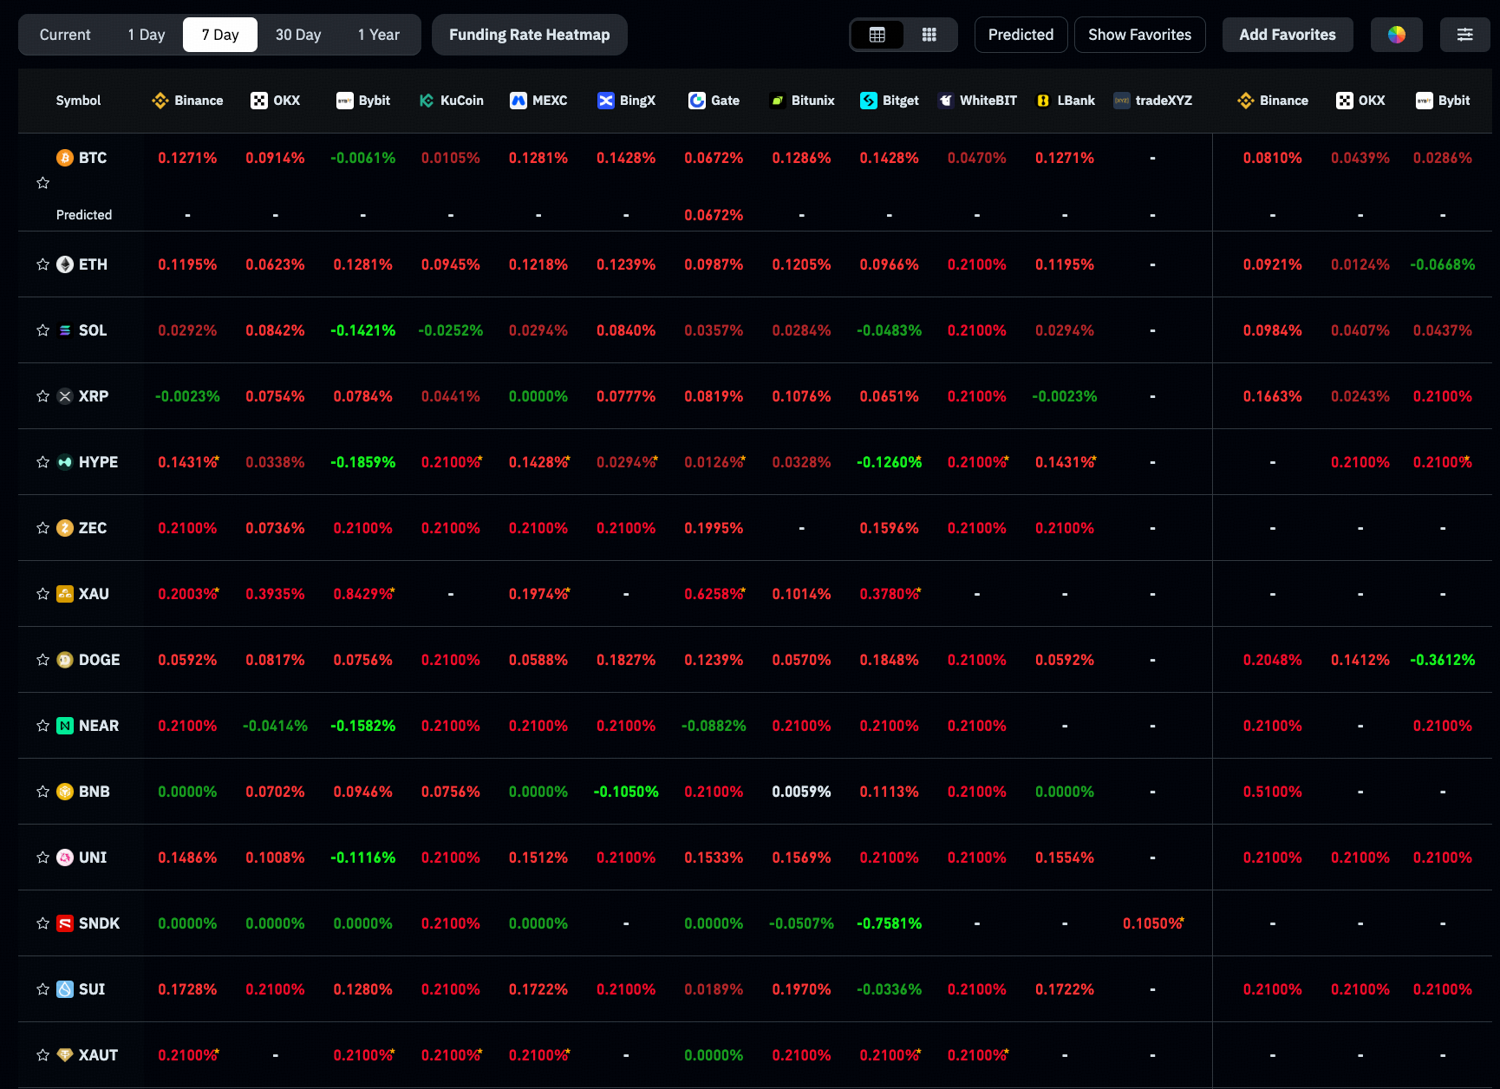
Source: Coinglass
More importantly, ETF flows have remained positive through the volatility. Inflows continued even as Bitcoin retreated from above $87K toward $84K, suggesting that the macro-driven selloff has not yet triggered a comparable reversal in longer-term capital flows.
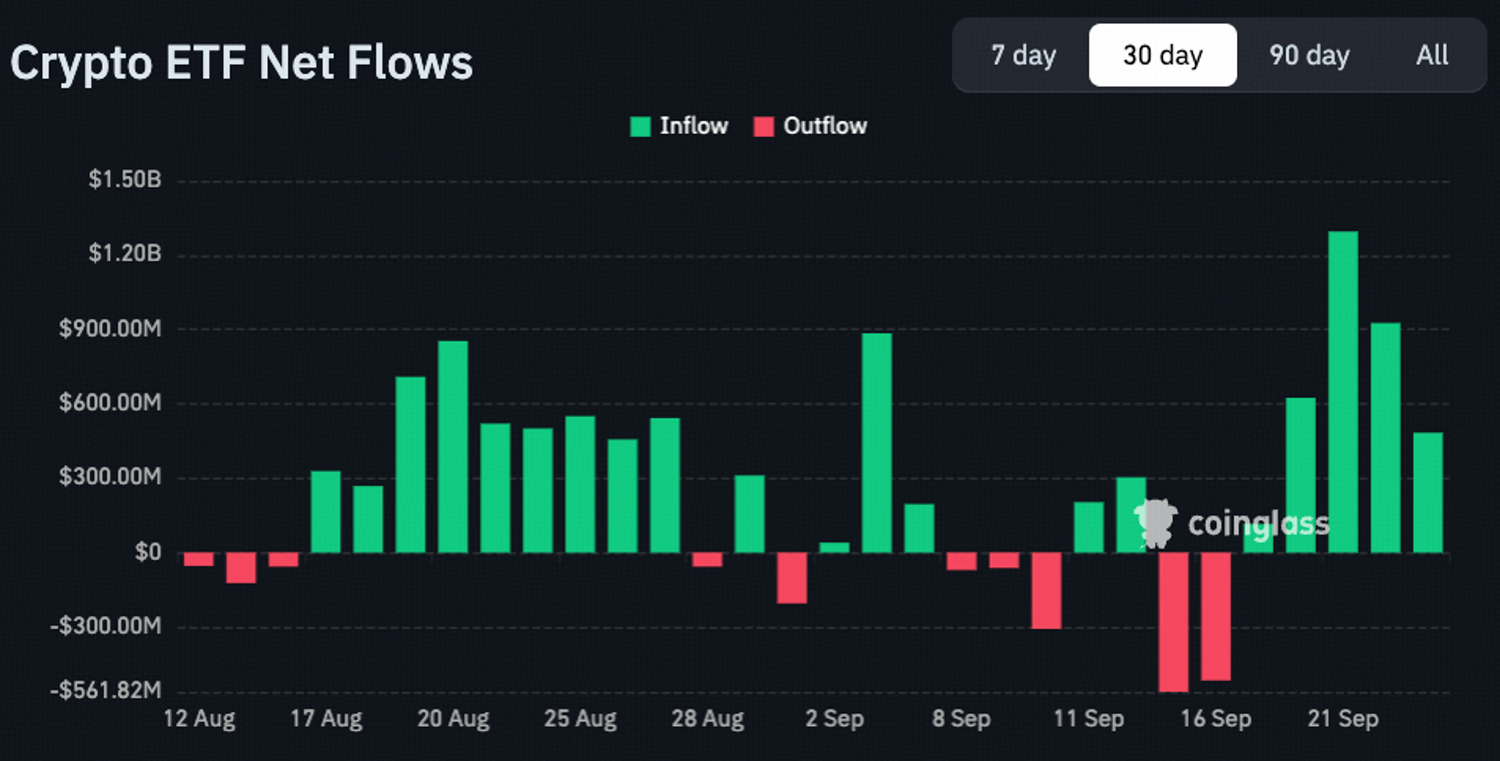
Source: Coinglass
Taken together, the macro shock has pulled prices lower, but it has not yet broken the underlying bullish structure. Leverage has come down, funding remains positive, and ETF demand has continued through the correction.
Week Ahead
- Sep 30: US August PCE
- Oct 1: US September ISM Manufacturing PMI
- Oct 2: US September Nonfarm Payrolls
Friday's payrolls is the first hard read on the labor market since the Fed's Sep 16 hike. A hot flash PMI on Sep 23 pushed October hike odds from near 50/50 to roughly 70% and the 10-year yield to its highest since 2007, so the bar for a hawkish surprise is now high.
A soft print would be the first thing in a week to pull hike odds and yields back down. Fewer hikes priced in means a better backdrop for risk assets, including Bitcoin and AI stocks.
Disclaimer: The information provided herein does not constitute investment advice, financial advice, trading advice, or any other sort of advice, and should not be treated as such. All content set out above is for informational purposes only.